 Austria
 Belgium
 Denmark
 Finland
 France
 Germany
 Greece
 Iceland
 Ireland
 Liechtenstein
 Netherlands
 Norway
 Poland
 Portugal
 Spain
 Sweden
 Switzerland
 Turkey
 United Kingdom
 Australia
 Fiji
 Hong Kong
 India
 Indonesia
 Japan
 Malaysia
 New Zealand
 Philippines
 Singapore
 Thailand
 Brazil
 Chile
 Colombia
 Mexico
 Peru
 USA
 Bahrain
 Israel
 Morocco
 Oman
 UAE
 Saudi Arabia
 Tanzania
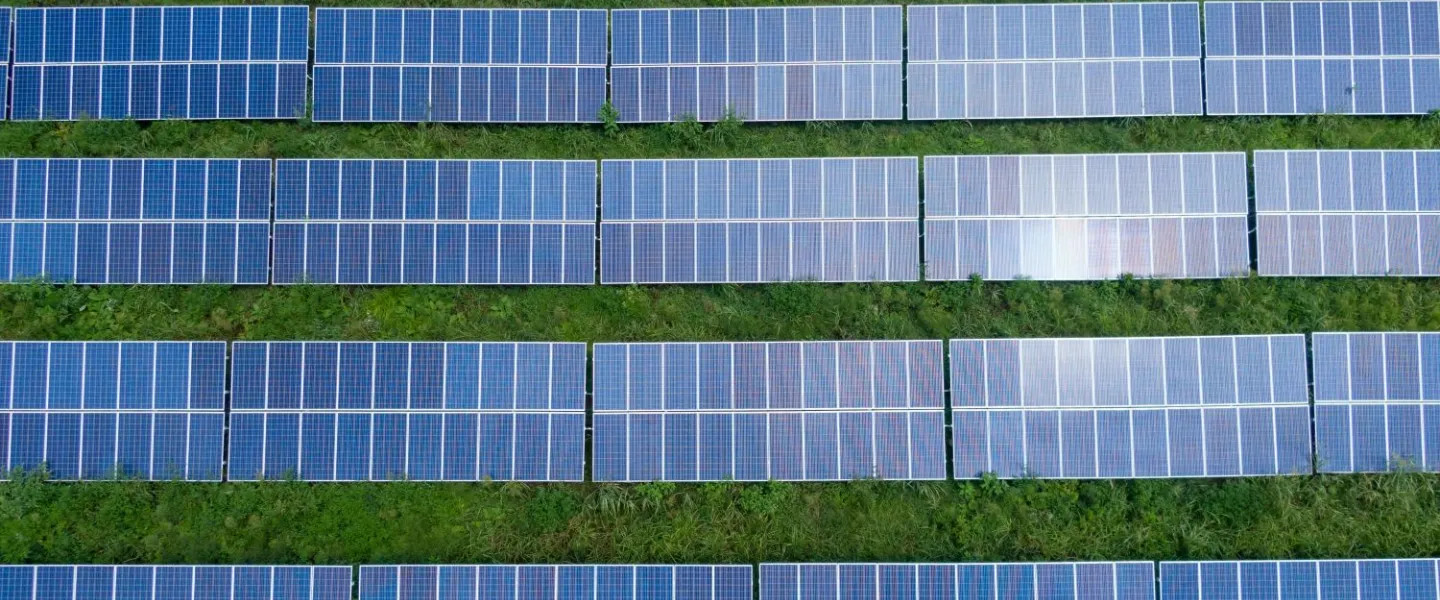
Photovoltaic Insurance
A thorough understanding of your sector, coverage tailored to your equipment and associated losses.
What guarantees to secure your solar projects?
The spectacular development of photovoltaics has transformed the risk profile associated with solar projects. Today, a photovoltaic power plant represents much more than an energy production installation: it is a long-term investment whose profitability depends on its ability to produce continuously.
Among climate risks, material damages, and operational challenges, the quality of insurance coverage has become a key factor in securing projects. The continued growth of the French park, which exceeded 33 GW* as of March 31, 2026, illustrates the strategic importance of these assets.
It is necessary to identify the guarantees that are truly adapted to the specificities of photovoltaics.
Not all insurance policies cover the risks to which solar installations are exposed in the same way, from construction to operation. This is precisely where specialized brokerage support makes a difference.
* Dashboard: Photovoltaic solar - First quarter 2026 | Data and statistical studies
Understanding all the risks associated with a photovoltaic installation.
A photovoltaic system combines sensitive electrical equipment, permanent exposure to the elements, and financial considerations related to electricity production. These three characteristics create risks that standard contracts do not cover well or at all! A solar installation is exposed to a wide range of different types of losses:
Fire of electrical origin, often linked to a connection fault or a faulty UPS.
Storm and strong winds, which can tear off modules or damage supporting structures.
Hail, the first cause of damage on the panels themselves, with damages sometimes invisible to the naked eye but affecting performance, especially on older installations.
Theft of copper cables and inverters, particularly common in isolated ground-based power plants.
The particular case of climate events
Climate risk has become one of the major concerns for developers and installers. Hail episodes are increasing and affecting geographical areas previously considered less exposed.
A good photovoltaic insurance policy must therefore include:
- The coverage of progressive damage related to hail (micro-cracks affecting performance over time),
- A storm guarantee without excessive deductible.
- A business interruption clause that compensates for lost production during the restoration period.
A personalized support for your solar projects
Project developer, installer or promoter subject to the APER law: each profile has different insurance issues, in a market where the offer remains limited and technical.
Our team supports photovoltaic actors in placing their risks and managing their claims, with dedicated sector expertise.
Why trust us with the management of your risks?
Your ally against the banks
During the financing phase, banks impose their own insurance conditions, often standardized. We are by your side at every stage of the project's life: we negotiate these clauses to meet their expectations and defend fair conditions based on market conditions.
Your defender in case of a claim
In case of an incident (hail, storm...), we accompany you with insurers to defend fair compensation and avoid any underestimation.
A constant market watch
We monitor market developments, regulations, and insurance practices. This monitoring allows us to optimize your coverage and defend your interests over time.
Concrete service commitments
We are committed to the quality of monitoring, responsiveness, and transparency of our actions. Regular reporting, dedicated tools, and exchanges with insurers ensure effective management.
Frequently asked questions
The law on accelerating renewable energy production now requires commercial, industrial and logistics buildings, as well as large outdoor car parks, to install renewable energy generation systems or green shade structures.
For property developers and logistics companies, this requirement means that a building’s insurability becomes a key design consideration from the very earliest stages of the project.
Insurers are increasingly making their acceptance of risk conditional upon the implementation of strict preventive measures:
- Smoke extraction systems suitable for buildings with roof panels
- Unobstructed access routes for the fire service
- Roof partitions to limit the spread of a potential fire
- Detection and automatic cut-off systems in the event of an electrical fault
If these requirements are not anticipated, they can delay a project or significantly increase its insurance costs.