

 Austria
 Belgium
 Denmark
 Estonia
 Finland
 France
 Germany
 Greece
 Iceland
 Ireland
 Italy
 Liechtenstein
 Netherland
 Norway
 Poland
 Portugal
 Spain
 Sweden
 Switzerland
 Turkey
 United Kingdom
 Australia
 Fiji
 Hong Kong
 India
 New Zealand
 Indonesia
 Japan
 Malaysia
 Philippines
 Singapore
 Thailand
 Brazil
 Chile
 Colombia
 Mexico
 Peru
 USA
 Bahrain
 Israel
 Morocco
 Oman
 UAE
 Saudi Arabia
 Tanzania
Buildings Underinsurance Hub
Stay fully covered. Learn the key causes of buildings underinsurance and how to prevent it.
What is building underinsurance?
Building underinsurance is when a property isn’t insured for enough money to fully rebuild it if something goes wrong. If your building is underinsured and you need to make an (even partial) claim, your insurer may only pay a reduced amount because your cover doesn’t match the building’s true rebuild cost.
Approximately 70%* of UK homes are underinsured, leaving households exposed to significant financial risk. *Data published in September 2025
Why underinsurance happens
Your property might be underinsured for a number of reasons.
- People can confuse rebuild cost with market value, leading them to choose a ‘sum insured’ that’s too low for what it would actually cost to rebuild the property.
- Many people estimate the sum insured, meaning their figures are rough guesses rather than accurate assessments.
- Key policy requirements can be missed, such as listing high-value items separately or updating cover to account for inflation.
- Policies aren’t reviewed regularly, so cover doesn’t keep pace with rising rebuild or replacement costs.
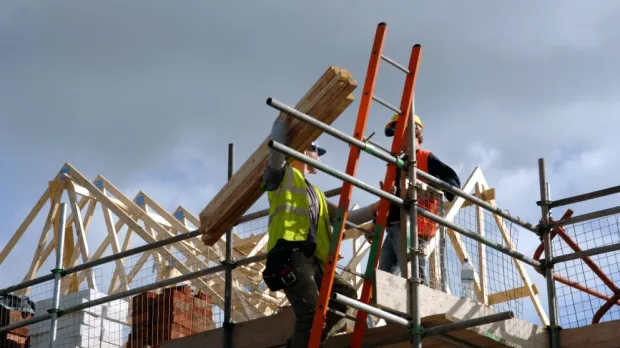
- Rising construction and labour costs can lead to rebuild values outpacing sums insured.
- Some might choose lower cover levels aiming to keep premiums down – unintentionally exposing themselves to underinsurance.
Consequences of underinsurance at claim time
If your property is underinsured, you might face serious issues when you need to make a claim. These can include:
- Reduced payout: Your insurer may only pay a proportion of the claim, even for partial losses.
- Out-of-pocket costs: You may need to cover the remaining repair or rebuild costs yourself. These costs can be substantial and may cause financial strain.
- Delays in claim settlement: Additional assessments or valuations may be required to determine the correct cover level.
- Parts of your claim may be declined: This can happen if policy requirements weren’t met - for example, if high-value items weren’t listed separately.
Worried about underinsurance?
Find out more about getting your property a new valuation.
Learn more about building valuations
Our underinsurance guides
A deep-dive into underinsurance including what it is, why it matters, business risks and examples.
Frequently asked questions
There are a few steps you can take to check if you’re underinsured.
- Confirm your rebuild cost: Use a professional valuation or a recognised rebuild calculator to ensure your sum insured reflects what it would cost to fully rebuild your property today.
- Review your policy details: Check if high-value items need to be listed separately and that your current cover matches what you own.
- Consider any recent changes: Building work such as renovations, extensions or new purchases can increase the value you need to insure.
- Check if your cover is index-linked: If it isn’t, your rebuild value may have been pushed above your sum insured by rising construction and labour costs.
- Speak to your insurer or broker: They can help assess your cover and recommend whether a valuation or policy update is needed.
It’s a good idea to review your cover at least once a year to make sure it still reflects the true cost of rebuilding or replacing your property. However, you should check sooner if:
- You’ve made changes to your property, including renovations, extensions or major improvements.
- The cost of building materials or labour has risen sharply. You might find this out through insurer updates, during your annual policy review or in a professional valuation.
- You’ve bought high-value items that need to be listed separately.
- Your policy isn’t index-linked (meaning it won’t automatically adjust for inflation).
It’s important to update your insurer or broker as soon as possible when your insurance details change. This helps ensure you remain fully covered and your policy stays accurate. You should update you details if:
- Your property has changed – for example, you’ve renovated, extended or added new features
- You’ve bought high-value items that need separate listing on your policy
- Your rebuild value has changed (following a valuation, or due to rising construction/labour costs)
- Your circumstances have changed (for example, how the property is used or who lives there)
- You’ve spotted an error or something no longer accurate in your documentation
At Howden, we work closely with specialist valuation provider Barrett Corp & Harrington (BCH) to offer two building insurance rebuild valuation services:
- Benchmark E-valuation – A fast, desk-based rebuild assessment that provides an accurate reinstatement value within 10%. It’s designed for simpler properties and typically completed within 72 hours.
- Building Insurance Reinstatement Cost Assessment (RCA) – A traditional, RICS-compliant site survey. Provides a detailed and fully validated rebuild valuation suitable for all property types.
These services help ensure your properties are valued correctly and that your buildings sum insured reflect the true cost of reinstatement.